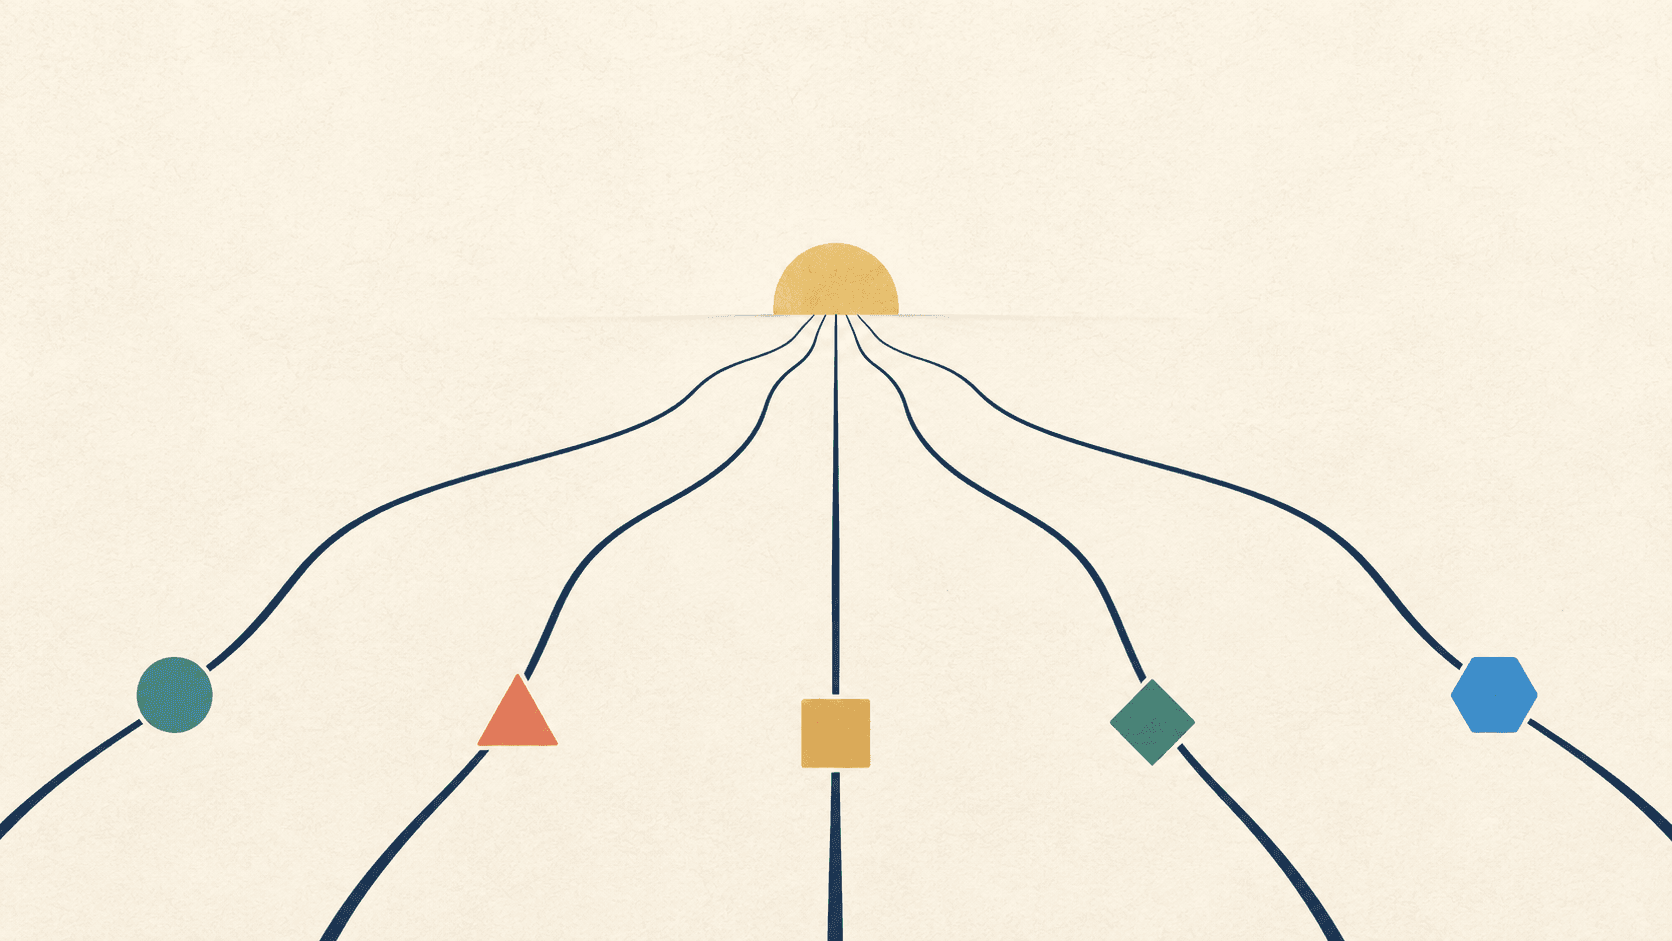
Change your FIRE path when the path's central bargain no longer fits: the spending level, continuing work, waiting period or margin it requires is no longer the trade-off you want or can sustain. Do not switch paths only because markets moved, a calculator date disappointed you or another FIRE label looks more successful.
Changing path is not admitting that the first plan failed. It is choosing a different way to combine money, time, work and sufficiency.
Compare the paths with one baseline: Open the Five FIRE Paths Calculator →
First decide what is actually changing
Before selecting a new label, identify the layer of the plan that moved.
- An input changed: spending, income, invested assets, return assumption or retirement date. This may need a recalculation, not a new path.
- The plan's fit changed: the numbers, capacity, meaning or resilience no longer line up. Start with FIRE Calibration and the guide to recalibrating a FIRE plan.
- The portfolio drifted: the investments no longer match the chosen allocation. That is a rebalancing question, not automatically a FIRE-path question.
- The central bargain changed: you want a materially different spending level, relationship with work, use of time or amount of margin. That is when a path comparison becomes useful.
Keeping these layers separate prevents a bad week at work from becoming an instant retirement decision, or a strong market year from becoming a permanently more expensive lifestyle.
What the five paths actually change
The labels are useful only when they expose the lever underneath them.
Lean FIRE changes spending
Lean FIRE reduces the recurring lifestyle the portfolio must fund. It can create a smaller target and an earlier date, but only if the lower budget is real, durable and leaves enough room for housing, health, tax, maintenance and irregular costs.
Moving toward Lean FIRE makes sense when lower consumption genuinely improves life or when simplicity creates valued freedom. It is a poor switch when “lean” means chronic fragility, hidden unpaid work or postponing every meaningful experience.
Traditional FIRE funds the chosen baseline
Traditional FIRE asks the portfolio to cover the full current spending baseline without required earned income. It is not morally superior to the other paths; it simply keeps the baseline and removes the planned work-income offset.
It can be a useful anchor because the other paths show what changes relative to it.
Fat FIRE changes spending and margin
Fat FIRE funds a higher level of spending or more explicit margin. The extra amount might support travel, paid care, family help, a costly location, hobbies or simply a wider buffer.
Moving toward Fat FIRE makes sense when the added spending is tied to a life you value and the extra accumulation period remains acceptable. It is not automatically safer: a larger target can require more years in an unsustainable work situation.
Coast FIRE changes future contributions
Coast FIRE reaches a point where existing capital is assumed to compound toward a later retirement target while current earnings cover current life. It exchanges future contributions for time and continued work.
It can fit someone who wants lower-pressure work or more present-day time but does not need the portfolio to fund life yet. Its weak points are the long compounding period, return assumptions and the continued need to cover current spending.
Barista FIRE changes post-transition earned income
Barista FIRE asks ongoing flexible income to cover part of spending, so the portfolio funds the remainder. It can create an earlier transition and preserve structure or social contact.
The path is only as strong as the income's durability, availability, taxes, benefits and time cost. A side income that consumes the same capacity as the old job has changed the label more than the life.
For a fuller explanation, read five ways people actually do FIRE.
Six signs that the path—not just an input—deserves review
1. The required life is no longer acceptable
You can still reach the target, but only by maintaining a work pattern, deprivation level or postponement that no longer feels worth the result. This is a meaning signal, not a motivation defect.
2. Capacity has changed for long enough to be structural
Temporary fatigue may call for rest. A sustained change in health, care duties, attention or available hours may make the path's contribution or work assumptions unrealistic. The distinction matters: redesigning a lifetime plan during one terrible week can be as unhelpful as ignoring a two-year mismatch.
3. The time horizon has changed
The most common reason Investor.gov gives for changing asset allocation is a changed time horizon. A FIRE path also depends on time. A nearer transition, a later retirement, a new education period or a changed family obligation can alter which combination of work and assets is plausible.
4. Earned income has a different role
Perhaps work became meaningful and you no longer want a full exit. Perhaps it became harmful and a later all-or-nothing exit is no longer tolerable. Perhaps flexible income proved reliable—or proved far more demanding than expected. These are path-level facts because Coast and Barista FIRE assign different jobs to future earnings.
5. The desired spending level changed for reasons that persist
A temporary bill is not automatically a new lifestyle. A permanent housing choice, care cost, geographic move or changed idea of “enough” may be. Rebuild the spending baseline from actual categories before choosing Lean or Fat FIRE by percentage alone.
6. More money created more choices, not just a closer date
A raise, business success, gift or inheritance can move every target closer. It may also make a different path possible: less work now, more resilience, more generosity or a higher-margin future. Do not assume the only rational use of a windfall is maximum acceleration. First verify ownership, tax and legal facts in your jurisdiction; then decide which freedom the money should serve.
Reasons not to change paths yet
Some triggers feel large but do not yet provide good evidence for a redesign.
- Recent market performance. Investor.gov warns against changing allocation simply because an asset category is hot. Likewise, one rally or fall should not automatically choose your life path.
- A single calculator result. A precise date inherits every assumption used to produce it.
- Comparison with another person. Their housing, family support, health, pension, tax and desired life are not your baseline.
- A short difficult season. Protect essentials and capacity first; decide later whether the change is structural.
- A new label with no operational difference. If spending, work, time and margin remain the same, renaming the path has not changed the plan.
William Bengen's original withdrawal-rate analysis is a useful reminder that averages can conceal damaging sequences of returns and inflation. It does not establish one universally safe rate or choose a FIRE path. If a path looks viable only because one withdrawal assumption is treated as a guarantee, inspect the assumption before changing your identity around the result.
Use a keep, adjust, test, switch or pause decision
Keep
The path's main bargain still fits. Update stale inputs and continue. Keeping a path after a serious review is an active decision, not inertia.
Adjust
The path fits but needs a different margin, date, savings rate or spending baseline. Change the parameter, not the whole strategy.
Test
The alternative looks promising but depends on an untested behaviour. Run a reversible experiment:
- live on the proposed Lean budget while preserving emergency savings;
- direct new contributions differently before selling taxable assets;
- try the hours required by a Barista income plan;
- take a bounded lower-contribution period before declaring Coast FIRE permanent;
- price the actual services or care behind a Fat FIRE margin.
A test should have a start, an end and an observation. “Try harder” is not a test.
Switch
The new path solves a durable mismatch, its assumptions are explicit, and its downside is acceptable. Save the new baseline and write down what would trigger another review.
Pause
The decision is important but the information or capacity is not yet available. Preserve liquidity and avoid unnecessary irreversible moves while you gather facts. This is especially reasonable after a bereavement, during severe burnout, amid a health crisis or while ownership and tax questions around a windfall remain unsettled.
A path-change matrix
Ask five questions before moving from one path to another:
- What lever changes? Spending, contributions, continued work, time or margin?
- What new dependency appears? Lower spending, market compounding, flexible income, more working years or a larger target?
- What evidence do I have? Actual expenses, a tested work pattern, updated benefits, current obligations or only an appealing projection?
- What is reversible? Contribution rates and trial budgets are often easier to reverse than quitting work, selling assets or moving.
- What would make me review again? Define the trigger now rather than during the next shock.
The CFPB's Revising Goals handout suggests checking whether goals still match current circumstances and values, including when circumstances improve. It also treats revising an unattainable weekly target as adjustment rather than abandonment. That is a helpful posture for FIRE: preserve the purpose while changing the mechanism.
Four common transitions and their real trade-offs
Traditional to Coast FIRE
You stop or sharply reduce retirement contributions and let existing capital carry more of the future burden. You gain present cash flow or time, but become more dependent on the assumed compounding period and continued current-income coverage.
Traditional to Barista FIRE
You transition earlier while retaining some earned income. The target falls, but the plan adds labor-market, health, schedule and income-reliability dependencies. Price the hours as carefully as the dollars.
Traditional to Lean FIRE
You lower the funded spending baseline. The target falls directly, but resilience may fall too if essential and optional spending were never separated. Test the budget with real irregular costs.
Traditional to Fat FIRE
You raise spending or margin and likely extend accumulation. The key question is not whether “more is better,” but whether the added capital funds something valuable enough to justify the extra time and work exposure.
No transition is automatically progress or retreat. It is a different contract.
Goal adjustment is not the same as giving up
A meta-analysis of goal-adjustment research found associations between goal disengagement, goal reengagement and aspects of quality of life across 31 samples. The evidence is not a command to leave every hard goal, and it does not prove that switching a FIRE path causes well-being. It supports a more modest conclusion: the ability to release an unattainable goal and engage with a meaningful alternative can be adaptive.
In FIRE terms, preserve the deeper aim—more agency, resilience or time—while allowing the route to change. A person can move from Traditional to Coast FIRE and remain committed to financial independence. Another can move from Lean to a higher-margin plan because lived experience showed that the original budget was too fragile. Neither has failed the idea.
A two-tool sequence for making the change
- Use FIRE Calibration to mark numbers, capacity, meaning and resilience separately.
- If the mismatch is path-level, use the Five FIRE Paths Calculator with one shared spending baseline.
- Change only the lever that defines the candidate path.
- Write down the new dependency and one adverse scenario.
- Prefer a reversible experiment before an irreversible action.
- Save the new baseline only after a separate confirmation.
This sequence prevents the comparison tool from choosing the question for you. Calibration identifies the mismatch; Five Paths makes the alternative trade-off visible.
Sources, evidence and limits
- The CFPB Revising Goals handout frames goal revision as an ongoing response to changed circumstances and values, including positive changes.
- Investor.gov explains when time horizon, risk tolerance, financial situation or goals may justify an allocation change and distinguishes that from rebalancing.
- Barlow, Wrosch and McGrath's meta-analysis reports associations between goal-adjustment capacities and quality-of-life measures; it does not validate a specific FIRE framework.
- Bengen's 1994 historical study demonstrates sequence and inflation sensitivity under its historical U.S. assumptions; it is not a universal withdrawal guarantee.
This article is general education, not personal investment, tax, legal, retirement or mental-health advice. Verify local rules and high-impact assumptions before making an irreversible decision.